Webinar - Professor Emilio Carrizosa returns to the CRC to finish what he started
13 October 2025
After his oversubscribed keynote presentation at the Credit Scoring & Credit Control Conference XIX, Professor Emilio Carrizosa returned to the CRC to deliver an extended webinar, Counterfactual Explanations: Models for Actionable and Explainable Decision-Making.
Counterfactual analysis is a powerful tool in Explainable Artificial Intelligence. Given a prediction model and a record (e.g., a client whose loan was denied due to a low score), a counterfactual is a minimally perturbed version of that record such that the same model would produce a sufficiently high score.
Within this framework, this talk addressed several challenging problems, including how to generate robust counterfactuals when the training data -and therefore the prediction model- may vary, and, taking a stakeholder perspective, how to obtain counterfactuals for multiple individuals while making the overall process explainable.
Professor Carrizosa, a distinguished data scientist and Professor of Statistics and Operational Research at the University of Seville, Spain, is also the President of the Spanish Network for Mathematics in Industry (math-in). His research, which focuses on modelling and optimization in Machine Learning with an emphasis on interpretability and fairness, has made significant contributions to the field. An author of over 150 papers, his work in optimization and data-driven decision-making has been recognized with numerous awards, including the SEIO medal and the prestigious SEIO-BBVA Foundation Prize in 2024.
We are pleased that Emilio has came back to satisfy the curiosity of the credit scoring and modelling community who want to learn more the importance and practicalities of counterfactuals.
Date: 23 October 2025 (2pm UK time)
Location: Online
Counterfactual Explanations: Models for Actionable and Explainable Decision-Making - Workshop October 2025 - Webinar
Thought Leadership in action
1 October 2025
At the Credit Research Centre, thought leadership means more than publishing research, it means shaping the conversations that influence practice, policy, and professional standards across the credit and financial services sectors.
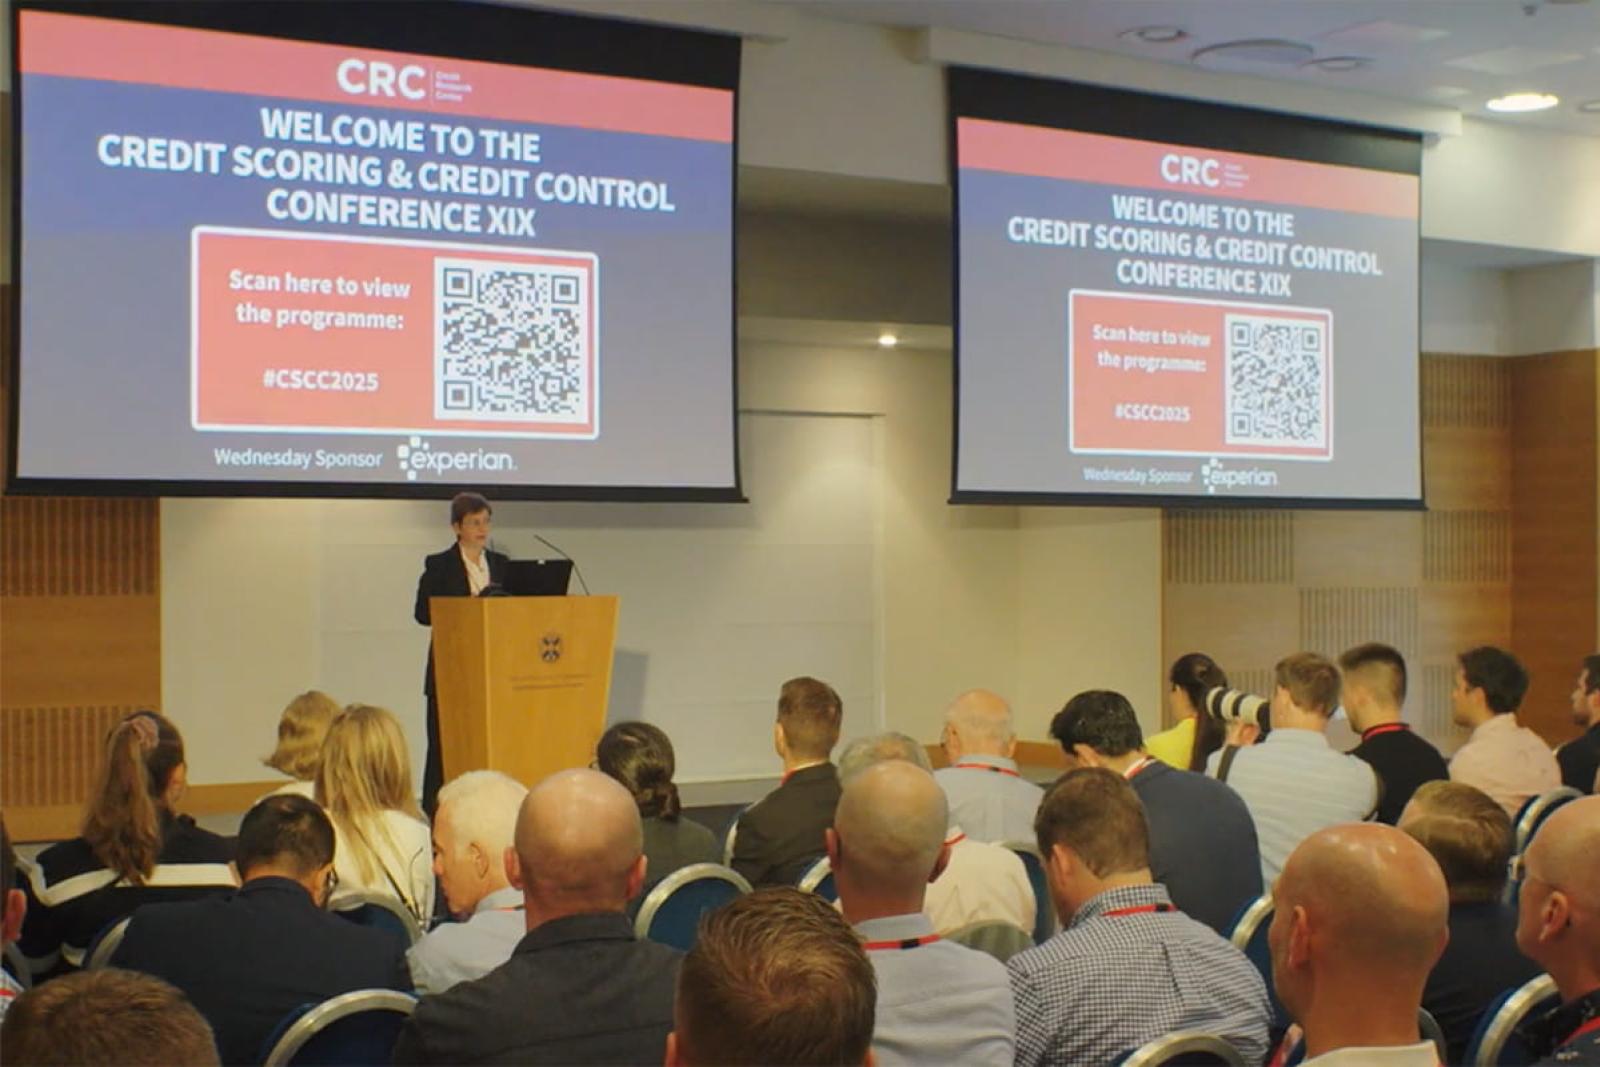
Our recent Credit Scoring & Credit Control Conference brought together academics, regulators, industry leaders, and practitioners from around the world to explore the evolving challenges of credit risk, model governance, AI in finance, and responsible innovation. Through keynote speeches, research presentations, and open discussion, the event demonstrated how rigorous analytics and real-world application must move forward together.
The video below captures the energy, insight, and collaboration that define CRC’s approach to thought leadership - connecting research with impact and strengthening the global credit community.
A More Holistic Approach to Banking Risk
6 May 2025
In today’s volatile economic environment, resilience in the banking sector is not just desirable—it’s essential. Banks are required to hold sufficient capital to absorb shocks, protecting against losses from loan defaults to ensure financial stability even in severely adverse conditions. How much capital they need is informed through “stress tests,” which estimate possible future losses – how severely things may go wrong – based on hypothetical adverse economic shocks.

Traditional stress tests focus heavily on macroeconomic variables like inflation, bank rate, unemployment, and GDP, but they often overlook a powerful predictor of financial distress: human behaviour. How individuals manage credit—especially under economic strain—can significantly influence default risk. How people behave in response to economic shifts—whether they draw more credit, alter repayments, or reduce their spending—can be just as impactful as the economic shifts themselves.
Recent research from Dr Viani Biatat Djeundje and Emeritus Professor Jonathan Crook at the University of Edinburgh’ Credit Research Centre addresses this oversight. The approach they propose blends behavioural data with economic indicators, to provide a more responsive and accurate model for assessing the impact of severe economic shocks. The implications could reshape how banks and regulators assess capital requirements and ensure long-term stability in an increasingly volatile global economy.
The Problem with Conventional Stress Testing
Stress tests are designed to answer one essential question: how likely is a bank to withstand extreme economic conditions? Will it remain solvent given adverse shocks?
Traditionally, regulators (and/or banks themselves) input severe but plausible values for macroeconomic variables to be used in models that predict the probability of default (PD) – the likelihood that someone will stop paying back a loan. This contributes to an estimation of a bank’s potential losses, and how much cushion it needs to withstand them. However, these models often freeze the human element —behavioural data— at static, historic levels, as though human responses remain constant regardless of circumstances.
This assumption is not only unrealistic—it’s risky.
Consumer behaviour often changes rapidly in response to economic downturns. For example, when the bank (interest rate) rises, it’s likely that more people will draw heavily on credit cards, miss payments, and/or shift their repayment habits. These behavioural shifts are not only predictive of defaults—they’re intertwined with the economy itself.
Ignoring this link can lead to stress test results that look fine on paper, but miss brewing risks in practice. As Djeundje and Crook argue, this disjunction results in stress tests that are less informative and, potentially, misleading.
A Smarter, More Realistic Model
To address these shortcomings, the researchers propose that current practices can be improved with a dynamic model that does two things simultaneously: it simulates both macroeconomic shifts and behavioural changes at the same time—and importantly, keeps them correlated. In other words, the model responds to external conditions like conventional models, but also assumes that people will change their financial behaviour in response to economic conditions, i.e. as one would expect a real person to react.
This new approach uses advanced techniques to simulate a variety of economic futures and predict how borrowers will behave under each one1. The model then estimates how many of these borrowers might default and calculates how much capital the bank needs to stay safe2.
One key innovation is the use of “mixed-effects autoregressive models”—a fancy way of saying the model remembers both the past behaviour of individuals and the wider economic environment. This allows banks to better forecast how account-level behaviours (like repayment amounts or credit limit usage) evolve.
What They Found: Behaviour Matters - A Lot
Using the real, anonymised, credit card data from over 100,000 accounts at a major UK bank, the study showed that including behavioural data made predictions significantly more accurate. Crucially it also revealed that when changes in behaviour are ignored—as is often the case in current stress testing practices—the risk to banks is systematically underestimated.
In fact, the model showed that Value-at-Risk (VaR)—a key measure of potential losses under severe circumstances —increased when behavioural uncertainty was included. Without it, banks may believe they are safer than they truly are. Moreover, over longer forecasting horizons, the difference in risk assessment widened, underscoring the growing importance of behaviour-based forecasting in long-term stress testing.
And this is not just an academic point. In a world of rising interest rates, geopolitical shocks, and consumer debt at record levels, misjudging risk can be catastrophic. Banks relying solely on macroeconomic stress scenarios may be holding insufficient capital reserves—especially during prolonged downturns.
The Importance of the Research
While this might sound like a technical shift in the back rooms of finance, the societal implications should not be underestimated.
- For consumers, better risk modelling may prevent banks from overextending credit or underestimating vulnerabilities—reducing the chance of crises that harm jobs, savings, and housing and the ability of the economy to function. There is never a bad time to reduce the likelihood of bank failure.
- For the banking industry, it’s a wake-up call to modernise models and bring behavioural science into the heart of risk management. The model also offers the opportunity for a competitive advantage.
- For regulators, this framework offers a more nuanced, representative tool to enforce financial resilience, namely it’s time to modernise stress testing protocols. Incorporating behavioural dynamics into supervisory models can help ensure capital buffers are both sufficient and robust.
As the world becomes more complex and interconnected, the old models aren’t enough. We need smarter stress tests that reflect how people actually behave—not just how the economy moves.
Conclusion: Modelling Risk in a People-Centred Economy
Djeundje and Crook’s research highlights a simple yet often neglected truth: you can’t separate the economy from the people living in it; financial systems are human systems. While economic indicators provide essential context, it is people—borrowers, consumers, workers—whose actions ultimately drive financial outcomes.
By combining behavioural insight with economic rigor, this new approach offers a clearer window into the true risks banks face—and a path towards increased financial security.
Reference
Djeundje, V.B. and Crook, J (2025) Incorporating behavioural and macroeconomic correlations for the prediction of bank capital for credit risk. Journal of the Operational Research Society , 1–15.
1 The proposed simulation framework:
- Models the macroeconomic environment using a sophisticated econometric method known as a Vector Error Correction Model (VECM), which accounts for relationships between variables like interest rates, GDP, and inflation.
- Forecasts individual behavioural changes using Mixed Effects Autoregressive Models. These models consider both past behaviour and the evolving economic context to predict how borrowers will likely respond over time.
2 The proposed simulation framework: By jointly simulating both behavioural and economic variables—and maintaining the statistical relationships between them—their model generates a more accurate distribution of future losses. This in turn yields a more reliable calculation of Value-at-Risk (VaR) and Expected Shortfall, two core metrics for capital adequacy.
Catarina Souza joins Credit Research Centre’s Research Advisory Board
28 February 2025
The Credit Research Centre (CRC) is delighted to welcome Catarina Souza to its Research Advisory Board. Catarina is a highly respected leader in risk management and currently heads the Model Development and Review division at the Bank of England.
With extensive experience in model risk management (MRM), regulatory oversight, and credit risk analytics, Catarina brings a wealth of expertise to the CRC. Her leadership in developing and reviewing financial models at one of the world’s most influential central banks will provide invaluable insights for our research initiatives.
Many will remember Catarina from the Credit Scoring and Control Conference XVIII, where she delivered a compelling presentation on The Evolving Role of Model Risk Management (MRM) in a Changing World: A Regulator’s Perspective. Her insights into the shifting regulatory landscape and the growing importance of MRM were met with great enthusiasm by academics and industry professionals alike.
As part of the Research Advisory Board, Catarina will contribute to shaping the CRC’s research agenda, strengthening collaborations between academia, industry, and regulators, and ensuring that our work remains at the forefront of credit risk and financial analytics.
We are excited to have Catarina on board and look forward to working together to drive innovation in credit research.
Announcing the First CSCC 2025 Keynote Speaker: Dr Stephen Miller
18 February 2025
The Credit Scoring & Control Conference XIX (CSCC) is proud to announce its first keynote speaker: Dr Stephen Miller.
Dr Miller will present a highly anticipated talk titled: “Machine Learning at the Credit Bureau: The Role of Predictive Modelling in a Regulated Landscape”.
A seasoned data science practitioner and researcher, Dr Miller brings nearly two decades of industry experience to the stage. Having spent the past 10 years at Equifax, he has played a pivotal role in leading innovation projects and technical teams. As a Data Science leader within the Equifax Global Data Science Lab, he has been at the forefront of advancements in predictive modelling, risk assessment, and regulatory adaptation.
His expertise is reflected in his extensive contributions to the field, including 13 patents and applications, as well as multiple presentations at prestigious conferences. Notably, his work on predictive modelling in affordability assessment earned him the CSCC 2023 Best Paper Award.
As the CSCC XIX conference approaches, attendees can look forward to Dr Miller’s insights into the evolving role of machine learning in credit scoring, especially in the context of regulatory challenges and industry innovation.
Stay tuned for more speaker announcements and event details!
Dr Viani Djeundje Biatat reflects on his project with the African Institute for Mathematical Sciences (AIMS)
29 January 2025
Dr Viani Djeundje Biatat, a Research Fellow at the University of Edinburgh's Credit Research Centre, explores the advancement of credit risk assessment in Africa, highlighting his teaching and mentorship at the African Institute for Mathematical Sciences (AIMS) and its impact on financial inclusion and the development of analytical skills across the continent.

The UEBS Credit Research Centre (CRC) is dedicated to advancing financial inclusion by sharing expertise in credit risk assessment, including credit scoring. Credit risk assessment plays a crucial role in reducing costs, minimising bad debt, and increasing credit availability. By doing so, it enables more individuals and businesses to access the funds they need, supporting purchases, investments, and efficient cash flow management.
The increasingly fast digitisation in African economies and growing need for credit makes credit scoring methods and management of scorecards a crucial topic for many African countries. It is with this in mind along with the growing demand for analytical skills in other sectors that I have contributed to the African Institute for Mathematical Sciences (AIMS) by teaching and mentoring graduate students across several countries over the past seven years.
Last year was particular, as Marc Gaudart, and Paul Randall of Trent Advisory Services, joined me to deliver the first credit risk course at AIMS in Cameroon. They brought valuable insights from their extensive experience in the lending industry, and their contributions enriched the learning experience of the students immensely. The CRC and AIMS were proud to support this initiative.
The motivations of students taking this course speak of their desire to expand their knowledge and their desire to apply the most cutting-edge techniques; from understanding the importance and role of credit risk for operational development in making informed decisions, to wanting to apply mathematical and machine learning techniques in the banking industry.
Personally I didn't know what credit risk was before but thanks to Viani, Marc & Paul, I can say I am a risk manager.Cameroonian data scientist and Mastercard scholar, course participant
Abraham Lincoln once said, "I will prepare, and someday my chance will come." It’s a pleasure to contribute to preparing these brilliant African students for their future. While many of them may feel that their paths ahead seem uncertain, I have no doubt that their "chances" will come. My hope is that many of them will go on to play pivotal roles in shaping the future of the continent and the world.
Viani Djeundje Biatat is a Research Fellow at the Credit Research Centre.